Fundamentals
What is organisational transformation?
Transformation as organisational development: how strategic self-renewal connects with structures, culture and leadership.
Read moreThe Corporate Sustainability Reporting Directive (CSRD) governs sustainability reporting in the EU: its aim, the ESRS, related rules and opportunities.
The Corporate Sustainability Reporting Directive (CSRD) is the EU directive on corporate sustainability reporting. It puts sustainability information on a par with financial information and makes it part of the management report. This overview explains what the CSRD means, what the EU aims to achieve with it, how the directive interacts with the ESRS, the EU Taxonomy and the SFDR, and what opportunities implementation offers companies.
The CSRD is a political instrument of the EU that puts sustainability reporting on a par with financial reporting. The directive requires companies to publish in detail in the management report how their business activities actually and potentially affect the environment and what actual and potential economic effects sustainability aspects have on the company. This twofold perspective is referred to as double materiality.
The CSRD is set out in EU Directive 2022/2464 of 14 December 2022. It amends the Accounting Directive 2013/34/EU and thus the requirements for non-financial reporting.
To ensure high quality and comparability of the data, the European Sustainability Reporting Standards (ESRS) were developed. They are an EU framework for standardising sustainability reporting and specify which sustainability information a company must report in order to meet the requirements of the CSRD. They were adopted with EU Regulation 2023/2772 of 22 December 2023.
The ESRS specify the extent to which companies report on the ESG topics that are material for them. The environmental area covers climate change, pollution, water and marine resources, biodiversity and ecosystems, and resource use and the circular economy. The social area covers the company's own workforce, workers in the value chain, affected communities, and consumers and end users. The governance area deals with business conduct.
The CSRD contributes to the implementation of the Green Deal. According to the European Commission, the Green Deal is a growth strategy intended to transform the EU into a fair and prosperous society with a modern, resource-efficient and competitive economy. By 2050, there should be no net greenhouse gas emissions, and economic growth should be decoupled from resource use.
The directive supports the financing of the sustainability investments planned within this framework. Because companies must disclose sustainability data, investors can assess and compare the sustainability of their investments. This transparency is intended to lead companies to focus more on long-term and sustainable developments than on short-term returns.
The CSRD is intended to work above all in conjunction with other EU instruments. The EU Taxonomy plays a central role. It contains a classification framework that defines the conditions under which an economic activity is to be regarded as environmentally sustainable. It focuses on six environmental objectives: climate change mitigation, climate change adaptation, the sustainable use and protection of water and marine resources, the transition to a circular economy, pollution prevention and control, and the protection and restoration of biodiversity and ecosystems.
The EU Taxonomy is taken into account in the CSRD and the ESRS. In line with the requirements defined there, companies state what proportion of their turnover, capital expenditure and operating expenditure is to be classified as environmentally sustainable.
The Taxonomy is also the basis of the Sustainable Finance Disclosure Regulation (SFDR). It requires financial market participants and financial advisers to provide information on the sustainability, sustainability risks and adverse sustainability impacts of their financial products. For this purpose, they can use the sustainability data published under the CSRD, in particular the information on the EU Taxonomy, and inform end investors accordingly.
According to the European Commission, this transparency is intended to help investors with their decisions and to steer private capital in such a way that the transition to a climate-neutral economy succeeds.
The EU adjusted the scope and timetable of the CSRD in 2025. Which companies must report and from when should be checked against the current legal position.
The CSRD requires companies to extend their management report to include sustainability reporting according to a standardised procedure defined in the ESRS. First, the materiality of sustainability topics must be determined. Then standardised data points must be reported on general topics such as governance and strategy and on the sustainability topics identified as material.
The effort involved in implementation can vary greatly. It depends on the company's level of maturity in sustainability, for example whether it already reports according to comprehensive reporting standards such as the GRI Standards. It also depends on whether and to what extent the CSRD requirements are seen as an opportunity to develop the company further towards sustainability.
Companies should therefore develop a clear picture of the opportunities that come with implementation and the extent to which they want to use them actively. The opportunities depend heavily on the environment: on the industry, the value-creation partners and the company's own intrinsic motivation. Depending on the current and future relevance of sustainability in the environment, four different levels of ambition can be defined, each of which shapes the implementation process differently.
First level of ambition, meeting compliance: companies can pursue the goal of meeting only the compliance requirements associated with the CSRD and thus satisfying the minimum requirements. The materiality analysis, data collection and report preparation are then designed efficiently and automated as far as possible, for example through the use of AI.
Second level of ambition, professionalising sustainability management: if sustainability is not yet effectively anchored in the organisation and existing resources are not yet used optimally, the implementation process connects the knowledge available in the company. This creates a shared understanding of the relevant sustainability topics and the associated objectives and focus projects. Responsibilities for implementation are defined.
Third level of ambition, developing differentiating features in the market: companies that expect high market potential for their sustainability performance and have not yet used it gather market expectations and assess market potential in the materiality analysis and stakeholder analysis. The stakeholder analysis should deliberately combine quantitative and qualitative surveys of the relevant stakeholders. The market-facing business units derive implications for service development from the results, develop measures and implement them. Data collection and report preparation are also designed with a view to marketing differentiating services.
Fourth level of ambition, developing the business model further: companies in a rapidly changing market environment whose future viability could be at risk or that are presented with major opportunities can use sustainability as a driver for developing their business model further. The first three levels of ambition focus on operational optimisation within the existing business model. Here, implementing the CSRD serves as a starting point for strengthening the organisation's market orientation, performance and capacity to learn.
This requires closely interlinked people and organisational development. The company is enabled to perceive impulses and opportunities from the environment and to process them both operationally and strategically.
The content and scope of the report are defined in the ESRS. The sustainability information is published as part of the management report within the annual financial statements. A uniform electronic reporting format applies to publication, the European Single Electronic Format (ESEF) in accordance with EU Regulation 2019/815.
CSRD reports are subject to an external audit requirement and need an assurance opinion from a statutory auditor.
As a systemic organisational consultancy, transformis supports the implementation of the CSRD. The transformis approach provides for a process that fits the needs and ambitions of the organisation in question, so that it can make effective use of the potential within its own organisation and in its market. Change and transformation processes are designed in the triad of strategy, organisation and people and supported from a single source.
This article is for general information and does not constitute legal advice for individual cases.
The CSRD is set out in EU Directive 2022/2464 of 14 December 2022. It amends the Accounting Directive 2013/34/EU and thus the requirements for non-financial reporting.
Sustainability information is to be published as part of the management report within the annual financial statements.
The reports are to be published in a single electronic reporting format, the European Single Electronic Format (ESEF) in accordance with EU Regulation 2019/815.
Yes, CSRD reports are subject to an external audit requirement and need an assurance opinion from an auditor.
Fundamentals
Transformation as organisational development: how strategic self-renewal connects with structures, culture and leadership.
Read more
Fachartikel
Organisational resilience meaning: how companies pick up signals of change, deal with shifting conditions and actively shape their own development over time.
Read more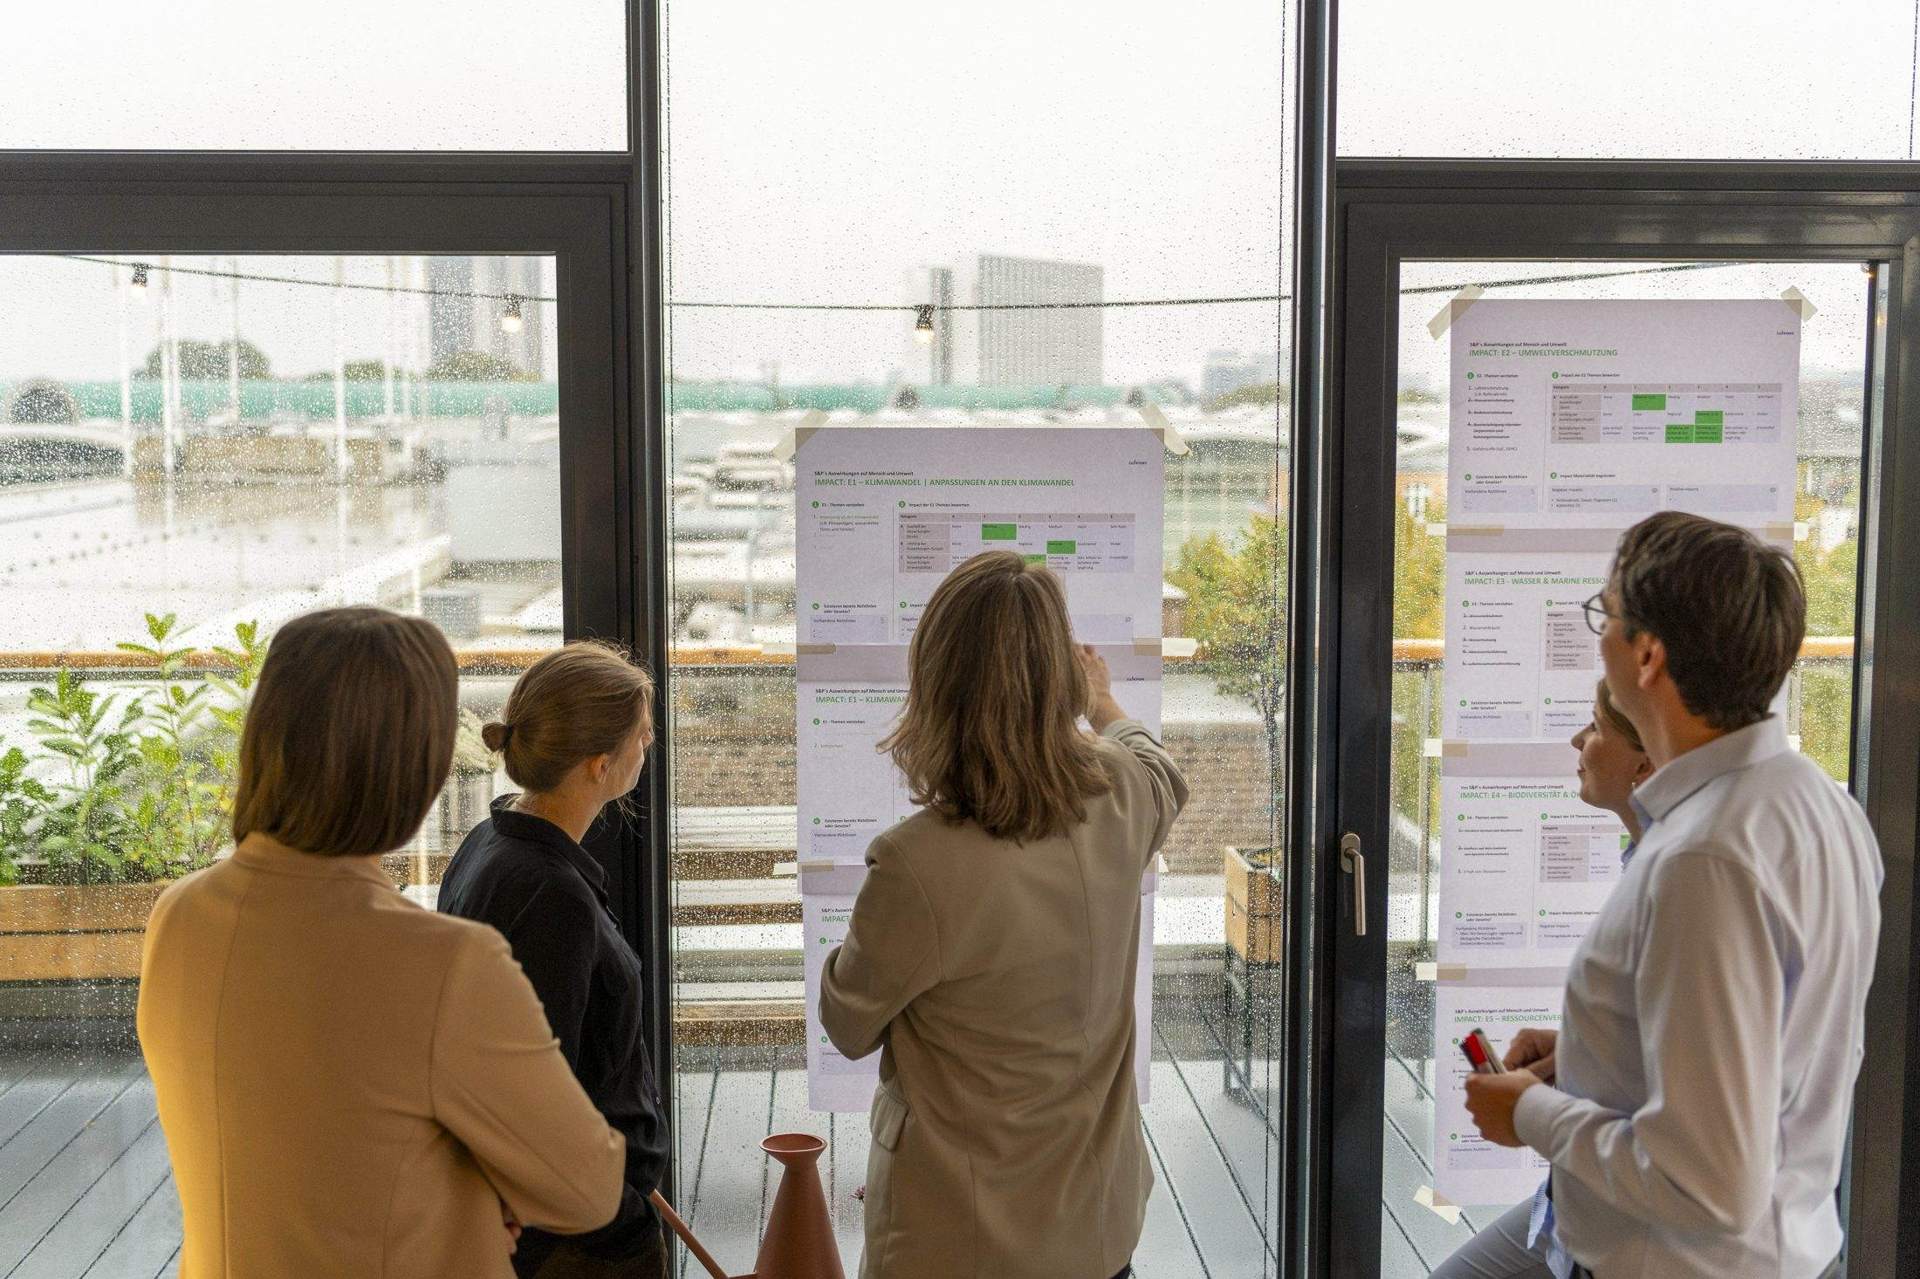
Fachartikel
Waiting times, duplicated work and coordination effort tie up time and resources. How to use them as starting points for developing your organisation.
Read more