Fundamentals
What is organisational transformation?
Transformation as organisational development: how strategic self-renewal connects with structures, culture and leadership.
Read moreA CSRD materiality assessment applies the principle of double materiality to determine, in four steps, which topics a company must report on.
A materiality assessment under the CSRD determines which sustainability topics a company reports on. It follows the principle of double materiality, looking both at the company's impact on people and the environment and at the financial effects of sustainability issues on the company. This article explains the concept, the two perspectives, a four-step approach and what the results mean for reporting and sustainability strategy.
The term materiality in the context of reporting originally comes from finance. Organisations such as the Financial Accounting Standards Board (FASB) or the International Accounting Standards Board (IASB) describe financial information as material if omitting or misstating it could influence the decisions of those who use this information. The CSRD builds on this concept of materiality to delimit the information to be reported.
The materiality analysis under the CSRD is a process for identifying and assessing sustainability topics in the environmental, social and governance (ESG) dimensions. The ESG topics assessed as material for a company form the content of the report. The materiality analysis is thus the basis of sustainability reporting.
The European Sustainability Reporting Standards (ESRS), established by the CSRD as the standards for sustainability reporting in the EU, require companies to carry out a materiality analysis regularly. The principle of double materiality applies, which distinguishes two perspectives.
Impact materiality, also called the inside-out perspective, covers the company's actual or potential impacts on people and the environment. Short-, medium- and long-term as well as direct and indirect impacts are considered. According to ESRS 1, this includes not only the company's own operations but also the upstream and downstream value chain.
Financial materiality, the outside-in perspective, covers the actual or potential effects of sustainability topics on the company. What matters are future cash flows and thus the influence on enterprise value, again short-, medium- and long-term and direct or indirect.
The aim of the double materiality analysis is to identify and assess a company's material impacts, risks and opportunities. The ESRS refer to IROs: impacts, risks, opportunities. The analysis leads to a prioritisation of sustainability topics. It is also an important input for developing sustainability targets and measures and thus for implementing the sustainability strategy.
The ESRS do not prescribe a process for how the materiality analysis is to be implemented. Companies can choose an approach that fits their business model and ambitions. Following the logical structure of the standards and EFRAG's implementation guidance on materiality assessment, four steps provide initial orientation: understanding the context, identifying actual and potential IROs, determining material IROs and reporting.
Step A, understanding the context, begins with an analysis of the value chain. The company examines its business model and business activities, outlines the upstream and downstream value chain of its products and services and clarifies what impacts its business activities have or could have on people and the environment. Further sources for the subsequent identification of IROs are regulatory requirements, media coverage, sustainability trends and studies, and existing analyses and evaluations of the company's sustainability.
A stakeholder matrix completes the value chain analysis. It shows who is or could be affected by the company's activities and its direct and indirect business relationships along the entire value chain.
In the second step, the company determines the impacts, risks and opportunities in connection with the sustainability topics defined in the ESRS. Its own activities, including the upstream and downstream value chain, are considered. Equally important are other sustainability topics that may not be included in the standards but are of great importance to the company.
In practical terms, this is an inventory of IROs. It ensures that no material ESG topics are overlooked and covers the company's entire sphere of action and influence, including relationships with all stakeholders in the upstream and downstream value chain. The result of step B is the company's “IRO long list”.
For reporting purposes, it must be disclosed for each IRO whether it relates to the company's activities or to the upstream and downstream value chain. In addition, each is classified in time as short-, medium- or long-term.
In this step, the topics that are material for the company are determined. The result is the company's materiality matrix and thus the basis for reporting. To distinguish material from non-material sustainability topics, quantitative and qualitative thresholds must be defined.
The assessment of the company's impacts on sustainability aspects, that is, impact materiality, follows the criteria of ESRS 1. Negative impacts are assessed according to scale, scope and irremediability, and potential impacts additionally according to their likelihood. For actual positive impacts, scale and scope count, and for potential positive impacts also likelihood.
The effect of sustainability aspects on the company, financial materiality, is assessed under ESRS 1 on the basis of the likelihood and potential magnitude of the financial effects.
Validating the results includes identifying outliers in the assessment, incorporating the different perspectives of stakeholders in the assessment through stakeholder dialogue, defining a method of relativisation and reaching a consensus.
In the fourth step, the topics identified as material are aggregated for the report and related to sustainability targets and measures. Companies subject to reporting requirements report continuously on progress towards their targets.
The entire process of carrying out the materiality analysis under the CSRD must comply with the requirements of the ESRS in a transparent, complete and comprehensible manner and be documented. It must be clear which part of the value chain the materiality analysis covers, which sustainability topics were assessed as material using which approach or method, and in what form stakeholders were involved in the process.
The CSRD introduced a binding European reporting standard, the ESRS. Every company that falls under the CSRD reporting obligation reports according to the principle of double materiality. With the help of the ESRS, material impacts and mutual influences between companies and the environment are to be reported comparably throughout Europe. A topic from the ESG dimensions is considered material if it falls under financial materiality, under impact materiality or under both.
The EU adjusted the scope and timetable of the CSRD in 2025. Which companies must report and from when should be checked against the current legal position.
The axes of the materiality matrix represent the impact materiality and financial materiality perspectives in gradations. The IROs determined in step C are placed in the matrix according to their assessment. All sustainability topics classified as significant and critical must be examined for options for action with which potential can be realised or risks reduced. The topics in the middle segment of the matrix should be examined for sensible measures, or at least continue to be monitored.
A realistic and transparent description of the measures for addressing the sustainability topics forms the basis for trustworthy stakeholder communication.
In terms of content, the analysis is based on the sustainability topics under the ESRS. In the standards, EFRAG has agreed on main topics in the areas of environment, social and governance, each containing further subtopics, so-called sub-topics and in some cases also sub-sub-topics.
The materiality analysis under the CSRD is the basis of sustainability reporting and at the same time an important input for developing a sustainability strategy. It is advisable to integrate carrying it out regularly into the routines and processes with which the company develops and implements its sustainability strategy.
Regular analysis of impacts, risks and opportunities is relevant for efficient risk management. It also helps to seize opportunities and open up new market and customer segments.
It is a process for identifying and assessing sustainability topics in the environmental, social and governance dimensions. The topics assessed as material form the content of sustainability reporting.
Two perspectives are considered: the company’s impact on people and the environment (impact materiality) and the impact of sustainability topics on the company (financial materiality). A topic is material if it falls under one or both of these.
Every company that is subject to CSRD reporting requirements reports according to the principle of double materiality. The ESRS require these companies to carry out a materiality assessment regularly.
No, companies choose an approach that suits their business model and requirements. Four steps provide orientation: understanding the context, identifying IROs, determining material IROs and reporting.
Fundamentals
Transformation as organisational development: how strategic self-renewal connects with structures, culture and leadership.
Read more
Fachartikel
Organisational resilience meaning: how companies pick up signals of change, deal with shifting conditions and actively shape their own development over time.
Read more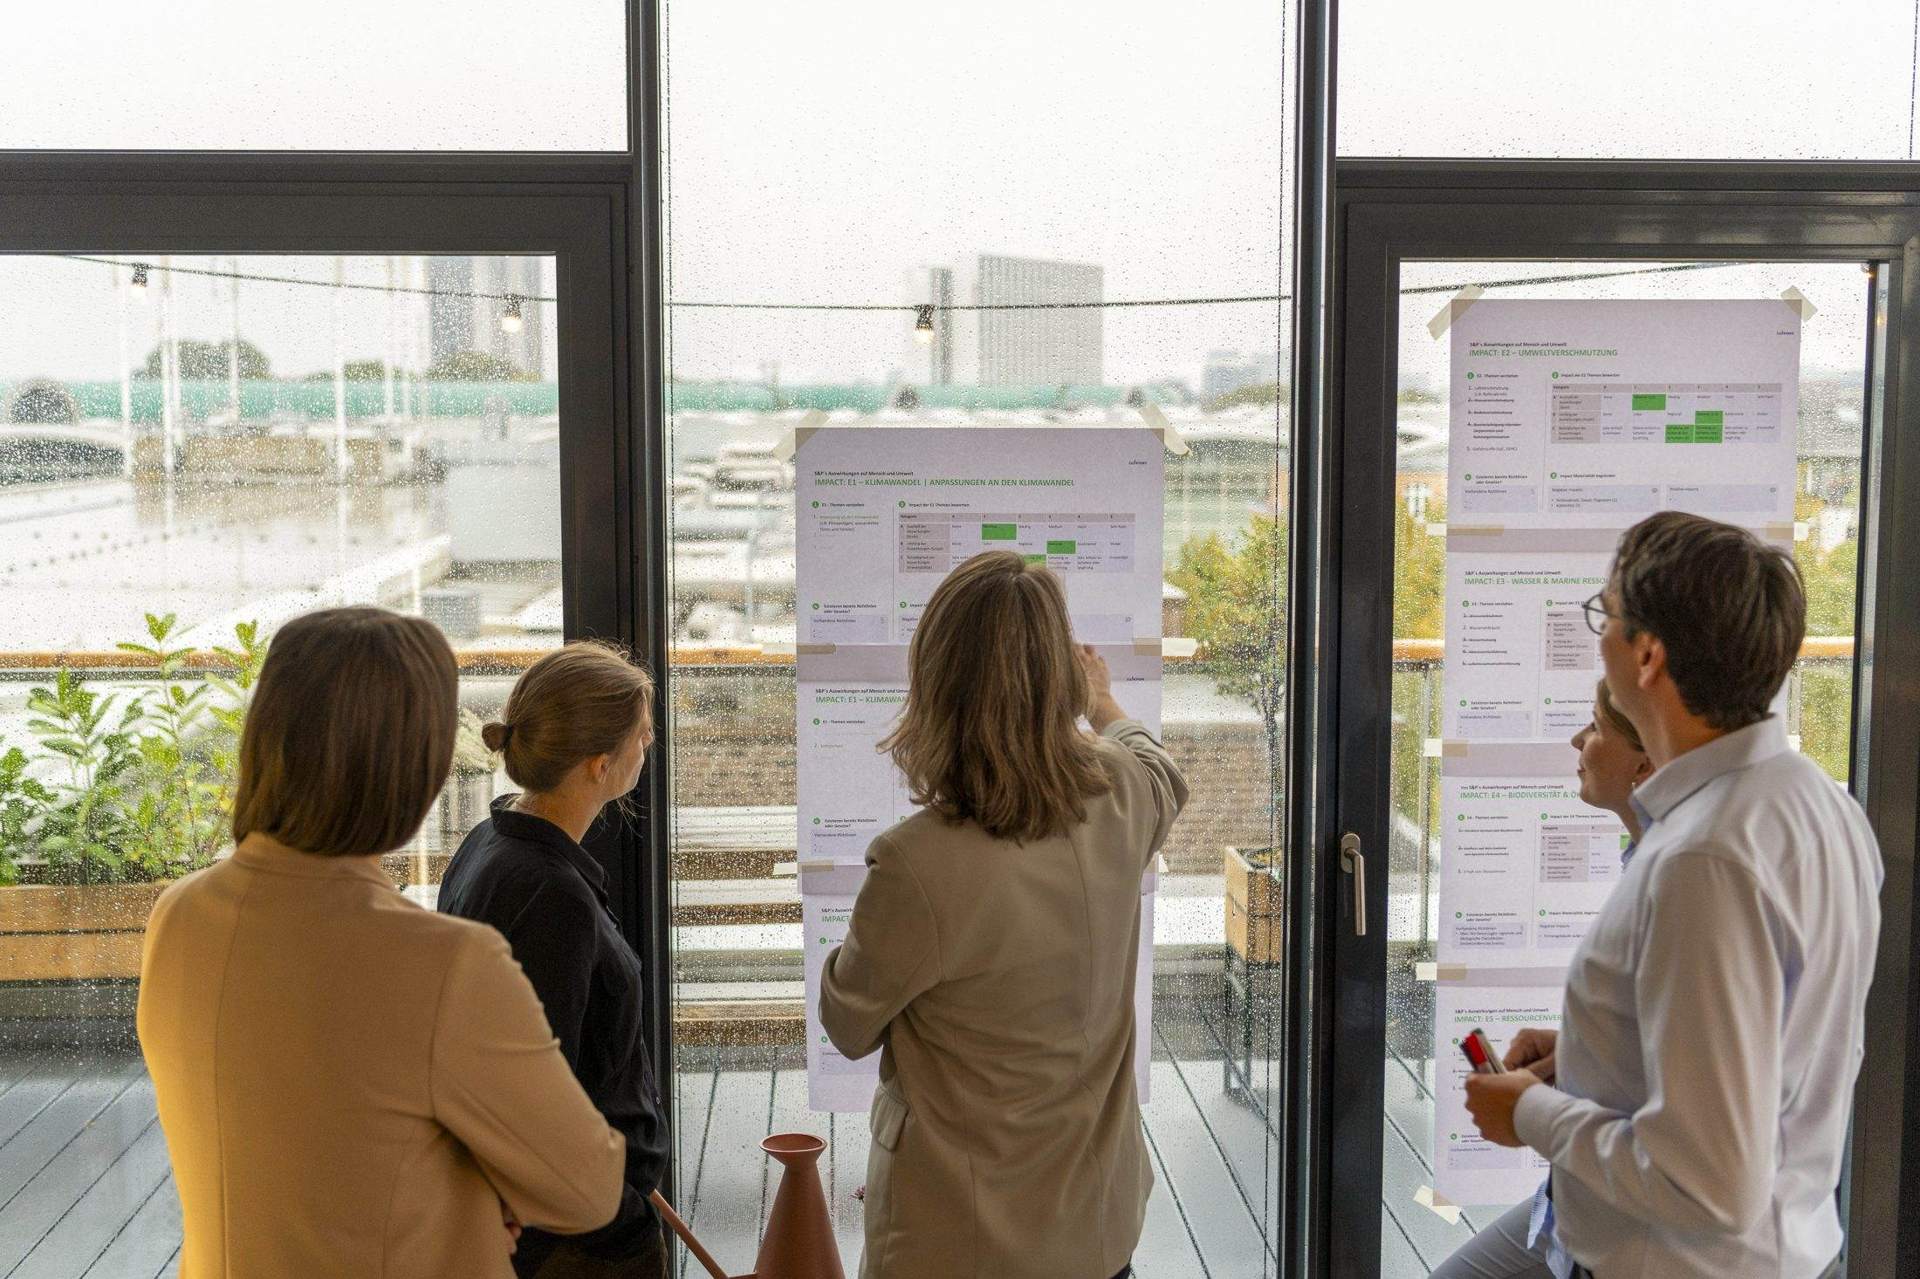
Fachartikel
Waiting times, duplicated work and coordination effort tie up time and resources. How to use them as starting points for developing your organisation.
Read more